Credit Unions

Top Credit Unions Thrive on Member Relationships

5 mins read
August 22, 2022
By
Megan Burr

Growth is the key driver of high performance for credit unions, according to analysis by Raddon. No big surprise there for any financial leader, but how did they find growth? And how do members, and credit unions’ relationships with them, play in?

Raddon found high-performing credit unions excelled at widening member usage of their products and services, managed higher ratios of profit-contributing households, garnered more risk-free revenue from fee income, and grew revenue without drastically scaling expenses.

Garnering Growth and Profitability

Helping members with a greater portion of their financial needs has clear correspondence to high performance and growth. The top 10% of credit unions were nearly 20% more likely to earn higher deposit and loan balances from members than others in the top half. If that seems like a slim advantage consider that those in the top 50% were 120% more likely than those in the lower 50% to grow deposit and loan relationships.

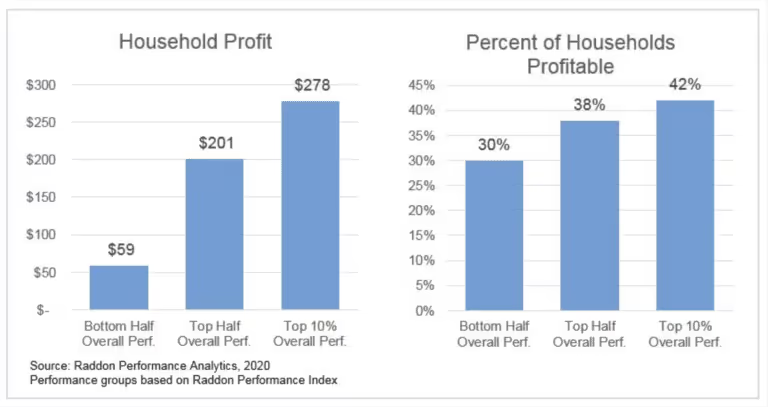
Profitable households also subsidize far fewer unprofitable households at top performers. Whereas at lower-ranking credit unions, only 30 percent of households were profitable – the remaining majority of their members do not generate enough margin income or non-interest income to offset the costs of servicing their accounts. While even top performers still subsidize the majority (58%) of households, profitable households make up 40% more of their member base compared to the bottom 50% of the institutions.
Relationship Builders

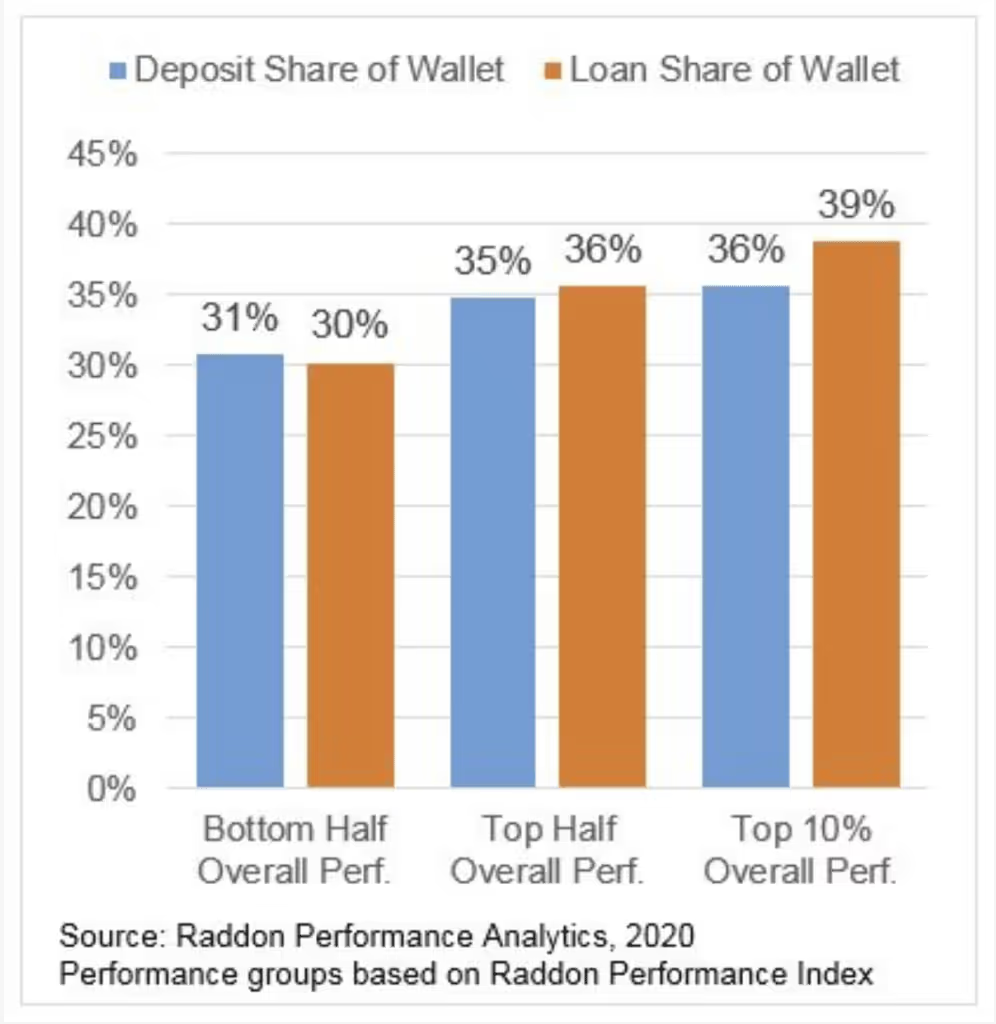
High performers received significantly greater shares of members’ deposits and loans.

For example, at high-performing institutions, nearly four out of 10 (39%) of member households’ total loan balances were with the institution, with the remaining 61% assumed to be with competitors.

In contrast, the bottom half of credit unions garnered only 30% of members’ total loan balances – a 30% shortfall compared to their peers.
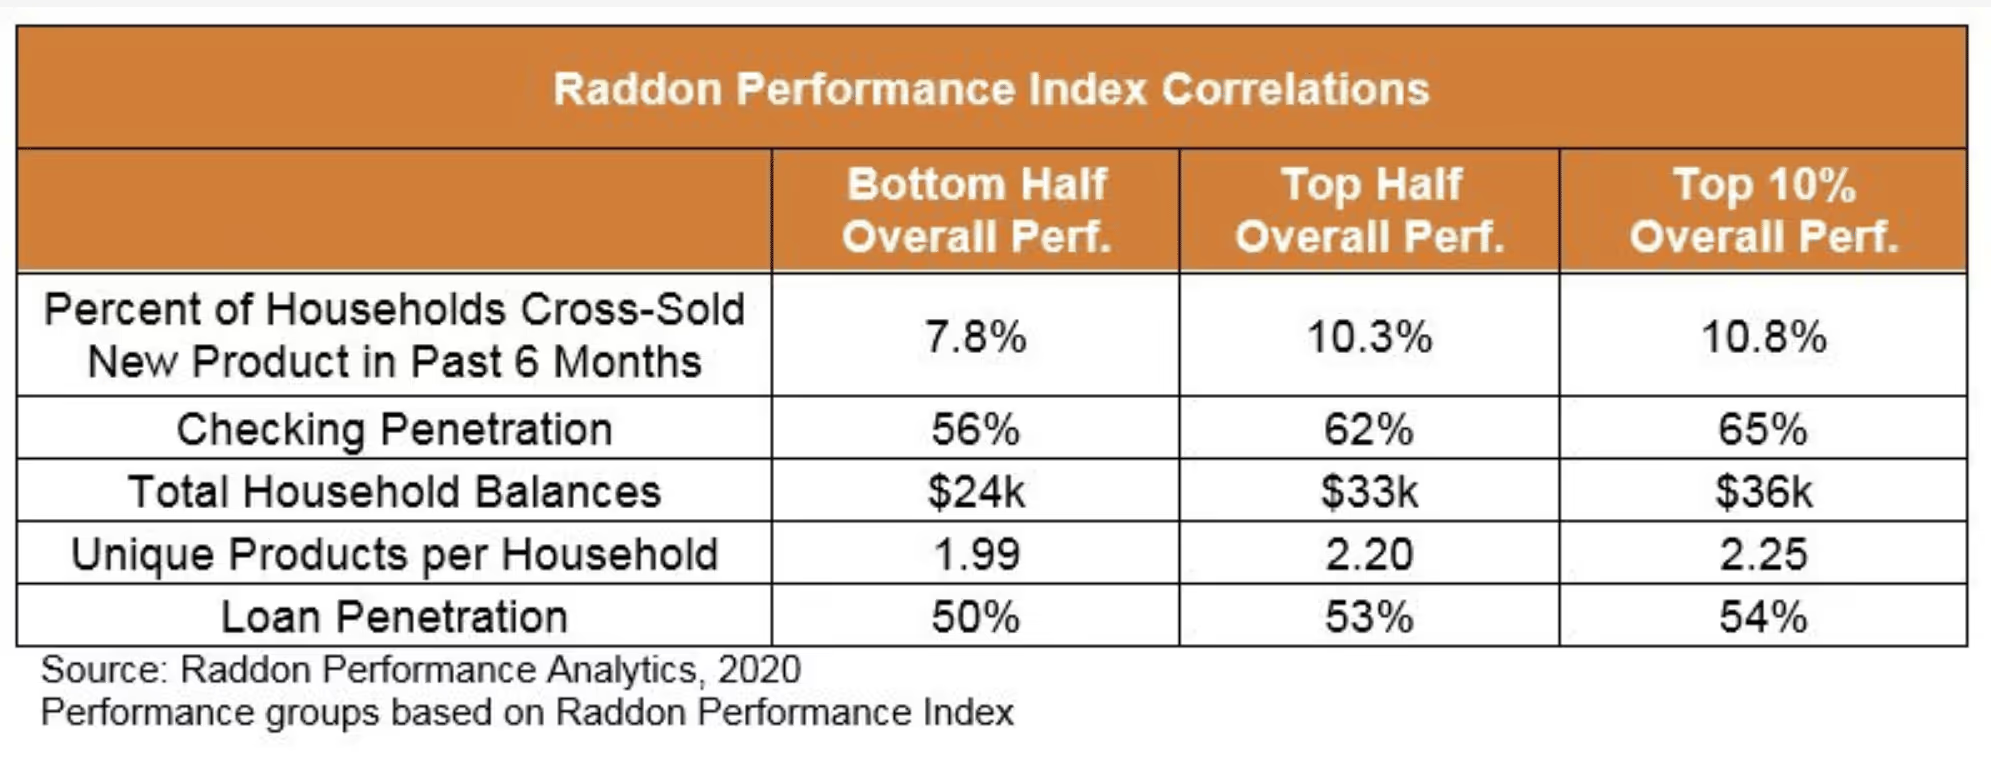
High performers also depended on broader member utilization of their products and services. Notably, the top 10% of credit unions “cross-sold” a new product to 10.6% of their membership within the past six months. The cross-sell rate declines by nearly 38.5% for lower-ranked credit unions to 7.8%
Raddon3

Performance is a function of a credit union’s ability “to develop deeper member relationships,” Raddon reported. Aside from the number of services used by a member, deeper relationships meant greater usage of products and services that generate non-interest income.

More fee revenue, though, was not necessarily about having more fees or higher fees, “it is the reflection of having stronger consumer engagement and more diversified sources of non-interest income,” Raddon analysts wrote.

When an institution is good at widening member use of its services, it is far more likely to provide members its investment services, which generate more fee income than other services. More robust levels of checking penetration offer non-interest income opportunities as well (see the table above), such as debit and credit interchange revenue. These fee sources also are not double-edged swords. They generate non-interest incomes without taking money from members’ accounts in a way they perceive as punitive.

High-performing credit unions earn 38% more non-interest income per household than their counterparts.

Scaling and Efficient

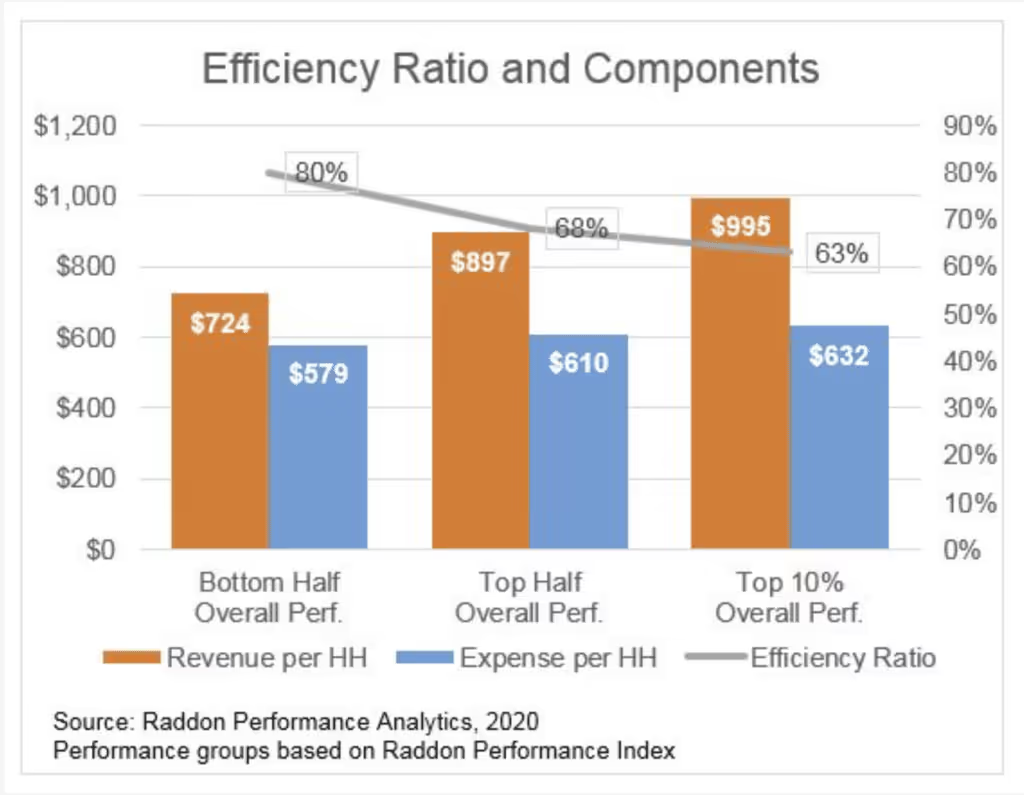
High-performers are more efficient than peers.

Calculated as total expenses as a percentage of total revenue, efficiency comes from reduced expenses, increased revenue, or a combination of the two. As the adage says: You can’t cost-cut your way to growth and profitability. High-performers do control costs, but their efficiency comes from generating significantly higher levels of revenue per household relative to their costs. They show credit unions are better off earning their way to better efficiency than simply cutting costs.

“For most organizations, expenses can be reduced by only so much before the reduction has an impact on service levels or growth opportunities,” Raddon explained in its report. “Deposit rates can be cut by only so much before the cost of funds hits a virtual floor.”

Because revenue is 37.4% higher at high-performers, they are still more efficient than their peers, even though they spend 9% more.
High-Performance Road Map

Credit unions need to follow the roadmap of high-performing credit unions, especially as interest rates and economic conditions change. Rising interest rates offer opportunities to grow earning assets at a higher margin, even while economic conditions may or may not support loan growth. Improving at serving current members for all borrowing needs – especially those that overlap with the institution’s offering – insulates growth in challenging economics, and supports more growth in favorable environments.

The story is similar for cost of funds and margin, loan growth becomes even more valuable when institutions stave off margin pressures from deposit price competition. When credit unions manage deposit retention and growth at an acceptable cost relative to their asset-liability strategies, greater profitability is within reach. Non-interest income also is the single best protection for profitability in times of margin compression.

As credit unions win consumers over – especially when they begin to see the credit union as their primary financial provider (PFI) – they become true members. Rather than simply keeping a share account, they use the institution for major financial milestones. When every major tactical contributor to high-performance is member relationships – their depth, profitability, and efficiency – leaders need to make building those relationships their focus.

This article is edited and republished with permission from Raddon, a Fiserv Company. The findings reported are results published by Raddon for its Crystal Performance Award, an annual recognition for credit unions.
‍

Resources

Related posts

AI

Introducing the 10X Lender Podcast Series

5  mins read
Read more

With the age of superintelligence touching nearly every aspect of our lives, previous limitations to growth are suddenly being removed. In mortgage and lending, we see the opportunity for organizations to create productivity and real business outcomes that are exponential. In the 10X lender series, Total Expert Founder & CEO will sit down with industry leaders to dive into the real-world shifts happening and explore both the natural friction of immense change and the tremendous opportunities emerging. AI superintelligence touches nearly every aspect of our lives, and previous limitations to growth and opportunity are suddenly being removed. In mortgage and lending, we see the opportunity for organizations to increase productivity and create exponential business outcomes.

AI

The 10x Lender: Why AI Demands a New Mortgage Operating Model

5  mins read
Read more

Adding more people to your call center won’t drive the kind of growth you’re seeking. And neither will bolting an out-of-the-box AI onto your existing workflows. That’s the mindset behind becoming a “10x lender,” and the idea that our Founder & CEO Joe Welu unpacked in a recent conversation with HousingWire’s Allison LaForgia.

That shift isn’t incremental. In this new, AI-enabled age, lenders have a real opportunity to do more than simply iterate on processes that have been in place for decades—they can reimagine the entire engine that’s powering their businesses. AI assistants can text, call, schedule meetings, and share information with tens of thousands of borrowers at once. Pair that scalability with the contextual data Total Expert already holds, and your outreach becomes hyper personal, always relevant, and perfectly synchronized with your customer’s financial journey.

For loan officers, that means less time clicking through screens and more time building relationships and educating consumers. This shift isn’t about automating away the work; it’s about elevating your teams’ ability to execute on every possible opportunity.

AI

Why "Faster" Isn't the Goal: Joe Welu on Building Customer-for-Life Lenders with AI

5  mins read
Read more

Most lenders approach AI the way they've approached every technology upgrade for the last two decades: find the part of the process that's slow and make it faster. Total Expert Founder and CEO Joe Welu says that mindset, while understandable, is holding the industry back from the outcomes AI actually makes possible.

In a recent conversation with HousingWire, Joe unpacked the mindset shift he's been sharing with lenders all year: stop optimizing the old process and start reimagining it from a blank canvas.

The problem with doing the same thing “faster"

For years, lending organizations have measured technology's value by a simple test: did it get people to log in and complete a task? New dashboards, new buttons, and new workflows all designed to change human behavior just enough to extract a little more efficiency from the same process.

The catch, Welu explains, is that this approach caps out at the limits of human behavior itself. A loan officer forgets to follow up. A call center rep runs out of time in the day. A relationship goes quiet not because anyone did anything wrong, but because relying on people to be perfect and predictable was never a sustainable strategy to begin with.

What breaks when the old ceiling stays in place

Joe used an analogy at the 2026 HousingWire AI Summit to capture the stakes: a farmer who just got a bigger, faster horse looks to the neighbor’s field and watches them ride by on a tractor. Incremental improvements, like faster horses, were the best option for decades. That's not the case anymore.

The risk isn't hypothetical. We still see lenders asking AI to slightly improve an existing workflow, rather than asking what their workflow should look like with AI built in from the start. And the lenders who are still chasing incremental improvements will find themselves outpaced by competitors who were willing to embrace a new mindset, a new strategy, and new era.  

Joe also highlighted that speed and speed alone will not set you apart. Context will be the critical differentiator in an AI-enabled world. Being the first one to engage a borrower is great, but only if you actually have something to talk about. Historically, a legacy database only knew what a person remembered to type into it. If that information wasn't captured, the system, and the loan officer, wouldn't be able to use it for the next conversation.

Context is king, and the mindset shift that gets you there

This is where Joe took the conversation from diagnosis to direction. Total Expert's Customer IQ continuously aggregates zero-, first-, and third-party data to create a complete financial profile and interaction history for every customer. This provides lending teams with the context they need at the exact moment it matters, whether that's to a loan officer having a conversation or an AI agent handling a task automatically.  

To put things in a perspective that everyone can understand, Joe drew a comparison to how streaming platforms already personalize recommendations based on what the user has watched or listened to previously—i.e., context. When that context is missing, it's obvious and often frustrating. He argues borrowers feel that same disconnect when their lender's outreach doesn't reflect where they actually are in their financial journey.

This level of change doesn't happen without friction. There will be individuals, teams, and even entire organizations that resist this shift. But leaders have to be clear-eyed about the realities of how our industry is evolving and, more importantly, how consumer expectations are driving that evolution.  

The reframe Joe’s pushing lenders toward is to stop measuring success by tasks completed, and start measuring it by the lifetime value of the customer relationship. He calls this “turning relationships into appreciating assets," where organizations never lose a customer and continually find new ways to add value to that relationship over time, rather than treating every interaction as a standalone transaction.

The takeaway

AI doesn't create value on its own. It creates value when it's grounded in real customer context, embedded in the actual workflow, and pointed at a bigger goal than getting a task done faster. For lenders willing to rethink the engine itself, Welu says the payoff isn't incremental. It's the same seismic shift that farmers experienced when they realized that even the slowest tractor was more efficient than the fastest horse.

See Total Expert
in action

Create sustainable growth and increase loyalty with a Customer Operating System that’s purpose-built for financial institutions.
Schedule a demo